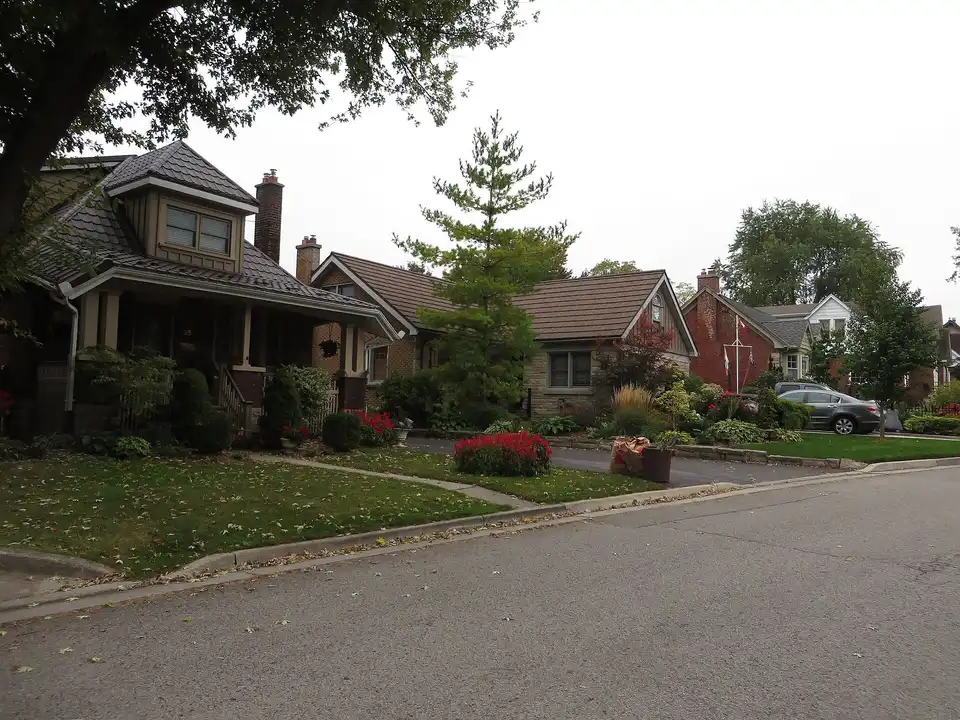
ReverseMortgageLondon.ca sets out what a reverse mortgage in London South could provide, from Wortley Village and Old South to Byron, Westmount, White Oaks and Lambeth. Every amount below uses September 2026 figures for the London South area, published by the London and St. Thomas Association of REALTORS (LSTAR).
London South had the most sales in September 2026
London South recorded 164 home sales in September 2026, up 19.7% from a year earlier and the most of London’s three LSTAR areas (LSTAR / CREA, September 2026 report). The average sale price was $608,872, down 4.1% over the year. The median was $557,500, down 7.1%.
The month itself was stronger. The London South average rose from $567,783 in August to $608,872 in September (LSTAR, Housing Sales Pick Up In September).
LSTAR’s benchmark for a typical London South home was $550,400, down 2.7% over 12 months and 0.4% from August (same LSTAR report). A benchmark is the MLS® Home Price Index value of a typical home, which makes it steadier than an average.
The bungalow benchmark rose most here
The London South bungalow benchmark rose 2.6% over the year to $565,000. That was the largest 12-month gain for any home type in the three London areas. Two-storey houses fell 6.2% to $663,900, townhouses fell 9.9% to $407,800 and apartment condos fell 9.3% to $302,500.
LSTAR’s benchmark London South bungalow has three bedrooms and about 1,225 square feet above ground, and it is 51 to 99 years old. Its benchmark two-storey house is 31 to 50 years old, with about 1,751 square feet above ground.
London South amounts at 65, 70 and 75
On the $550,400 benchmark, a reverse mortgage could provide up to about $278,000 at 65, up to about $291,000 at 70 and up to about $318,000 at 75. The age that counts is the youngest owner’s. The table applies the same percentages to London South’s other home types:
| London South home type | Benchmark | At 65 | At 70 | At 75 |
|---|---|---|---|---|
| Detached or semi house | $629,100 | $318,000 | $332,000 | $363,000 |
| Two-storey house | $663,900 | $336,000 | $351,000 | $383,000 |
| Townhouse | $407,800 | $206,000 | $216,000 | $236,000 |
| Apartment condo | $302,500 | $153,000 | $160,000 | $175,000 |
For example, say a widow of 75 lives in a Byron bungalow valued at the $565,000 benchmark. She could qualify for up to about $326,000. If she still owed $60,000 on a line of credit secured on the house, that $60,000 would be paid off first. Up to about $266,000 would remain for her to use, or to leave unused.
Each month’s interest goes onto the loan. Growth in London South home values often offsets some or all of that interest. Over the past year, London South bungalows gained value while most other home types lost it.
Heritage streets and newer suburbs
LSTAR doesn’t publish street-by-street boundaries for its three London areas, so treat the neighbourhood list as a guide. Wortley Village, Old South, Byron, Westmount, White Oaks and Lambeth all lie on the south side of the city.
London South, including the Wortley Village area, was transferred into the city in 1890 (Middlesex County history). Lambeth joined much later. London annexed almost all of Westminster Township, including the Village of Lambeth, on January 1, 1993.
The Wortley Village-Old South Heritage Conservation District covers 1,048 properties (City of London, heritage conservation districts). Council adopted it on September 18, 2014, and it was designated on June 1, 2015. The City describes a streetscape in place by 1915, with most homes built before the Second World War and the London Normal School as its landmark.
Farther out, Byron sits beside the Thames near Springbank Park and is mostly detached houses. Westmount and White Oaks are newer suburbs, built well after the older streets near downtown, with White Oaks just north of Highway 401.
Who looks at a reverse mortgage in London South
Owners of older homes in Wortley Village and Old South may face repair bills that savings can’t easily cover. Renovations to stay in your home explains how a reverse mortgage pays for that work.
Couples in Byron, Westmount and White Oaks sometimes face a move into care for one spouse. Long-term care in London and the house covers what happens to the home and the mortgage.
Owners with a larger lot in Lambeth or Byron sometimes want a unit for family on the property. Adding a unit in London sets out the City’s rules.
Long-term care and seniors’ programs in the south end
Long-term care homes with south-side addresses include Westmount Gardens (590 Longworth Road), McCormick Home (2022 Kains Road), Elmwood Place (3400 Morgan Avenue), Southbridge London (3715 Southbridge Avenue) and Village of Glendale Crossing (3030 Singleton Avenue) (Ontario Health atHome, London and Middlesex list). Meadow Park Long-Term Care is at 1210 Southdale Road East.
Dearness Home, at 710 Southdale Road East in the south-east, is the City of London’s own long-term care home, with 243 beds and an Adult Day Program (City of London, Dearness Home).
From July 1, 2026, a basic long-term care room costs $2,129.17 a month, and a private room $3,041.97 (Ontario, help paying for long-term care). The Byron Seniors’ Satellite runs programs for residents 55 and older at the Byron Optimist Community Centre, 1306 Norman Avenue (City of London, seniors’ recreation).
The cost and the comparison
In Ontario, your own lawyer typically charges about $800 to $1,200 for the independent legal advice appointment (ILA). Every one-time cost is listed in what a reverse mortgage costs in London. For a London South home, Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada, and the help is free. You get a recommendation based on your situation, even if it’s not a reverse mortgage.
What London South homes are worth in fall 2026
LSTAR's benchmark for a typical London South home was $550,400 in September 2026, down 2.7% over 12 months. On that value, a reverse mortgage could provide up to about $278,000 at 65 and up to about $318,000 at 75. On the area's $565,000 bungalow benchmark, it could provide up to about $286,000 at 65 and up to about $326,000 at 75.
| Area | Benchmark price | At 65 | At 70 | At 75 |
|---|---|---|---|---|
| London North | $613,000 | $310,000 | $324,000 | $354,000 |
| London South | $550,400 | $278,000 | $291,000 | $318,000 |
| London East | $432,300 | $219,000 | $228,000 | $250,000 |
Benchmark prices for September 2026 from the London and St. Thomas Association of REALTORS (MLS® Home Price Index: the value of a typical home of that type). The amounts apply about 50.5% at 65, 53% at 70 and 58% at 75, the top of what the highest-lending products allow. Amounts are rounded to the nearest $1,000. Your own home's appraisal sets the real number.
| Area | Benchmark price | At 65 | At 70 | At 75 |
|---|---|---|---|---|
| London North | $653,000 | $330,000 | $345,000 | $377,000 |
| London South | $565,000 | $286,000 | $299,000 | $326,000 |
| London East | $443,500 | $224,000 | $234,000 | $256,000 |
Benchmark prices for September 2026 from the London and St. Thomas Association of REALTORS (MLS® Home Price Index: the value of a typical home of that type). The amounts apply about 50.5% at 65, 53% at 70 and 58% at 75, the top of what the highest-lending products allow. Amounts are rounded to the nearest $1,000. Your own home's appraisal sets the real number.
London South neighbourhoods and landmarks
Wherever you live in London South, the help works the same way. Some of the neighbourhoods and places in this part of London:
- Wortley Village
- Old South
- Byron
- Westmount
- White Oaks
- Lambeth
- Pond Mills
Landmarks
- Springbank Park
- Storybook Gardens, in Springbank Park
- Wortley Road, the main street of Wortley Village
- London Normal School
- White Oaks Mall
- Byron Optimist Community Centre
- Lambeth Community Centre
How the help reaches you in London South
Help reaches London South homeowners by email, phone and video call, and grown children can be copied on every email. An appraiser comes to the house once. You meet your own lawyer for independent legal advice at any lawyer's office you choose, in Wortley Village, Byron or anywhere else.
What London South homeowners use the money for
- Renovations to stay in your home: Use the value of your London house for a stair lift, a walk-in shower or a bedroom on the main floor, and keep living there.
- Paying for care at home: Cover extra help at home from your London house, with monthly deposits or a lump sum, and keep living there.